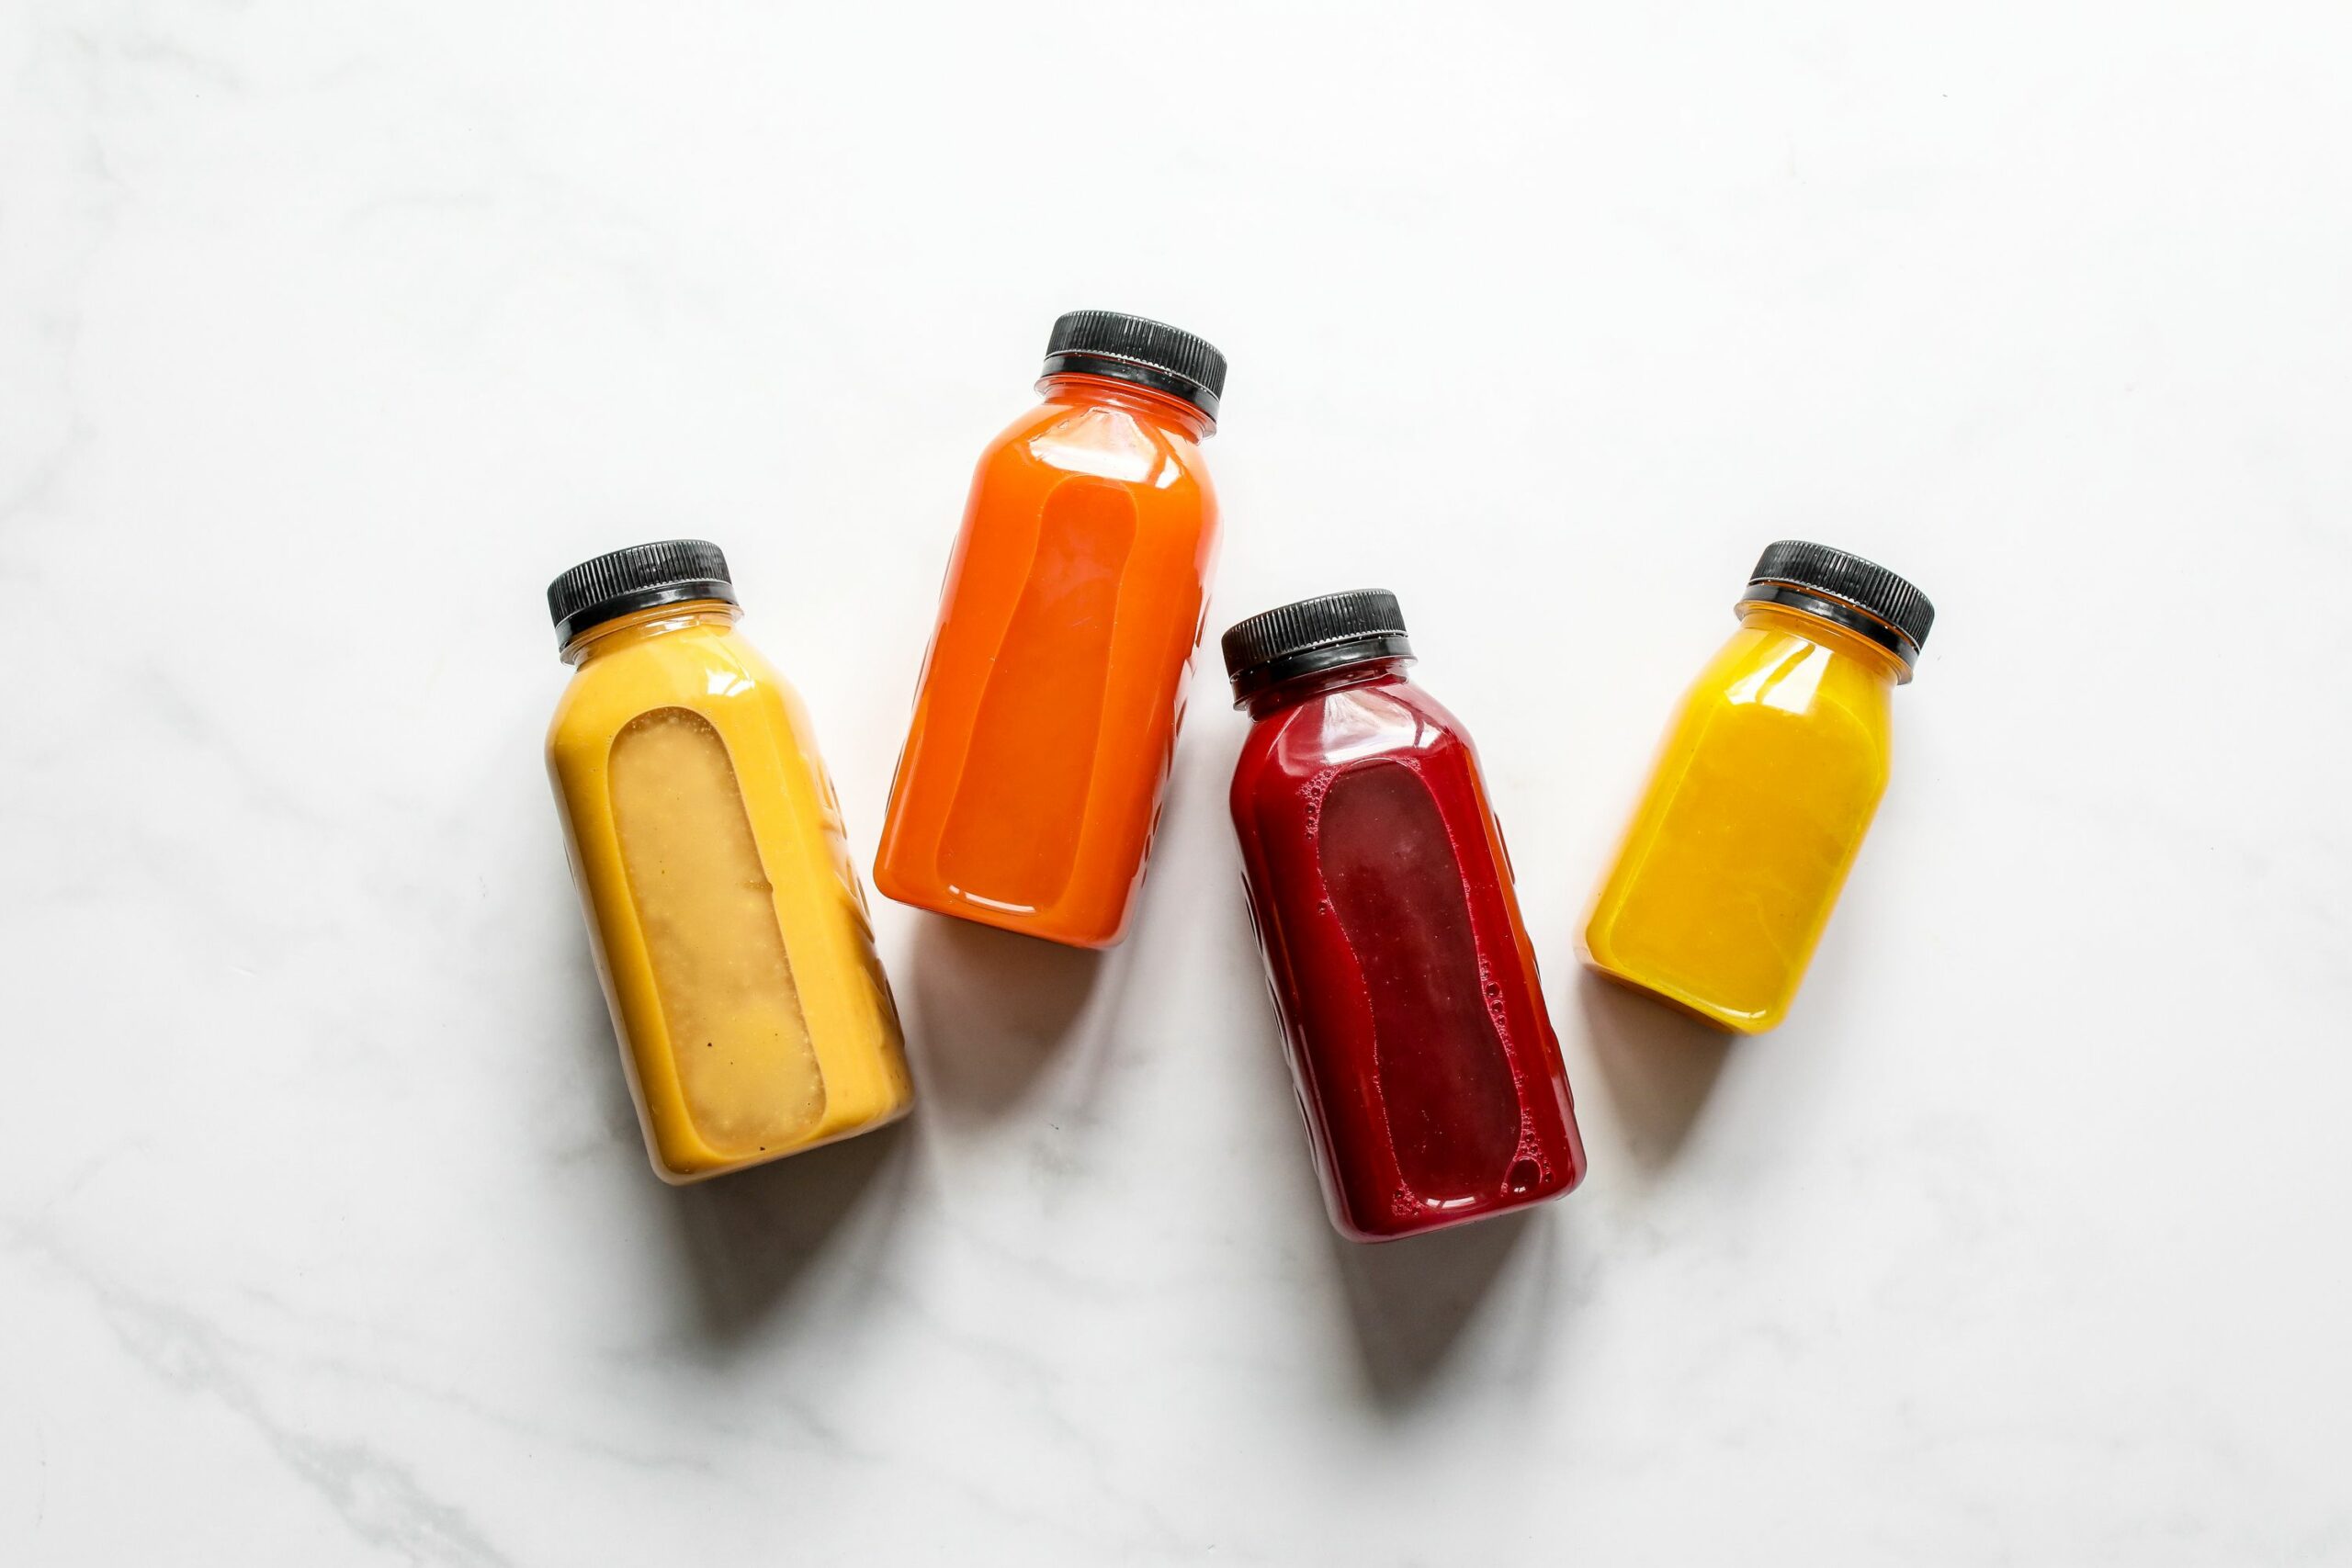

The Tribunal concluded that collagen beauty drinks should be standard-rated rather than zero-rated because, viewed objectively, they were marketed and purchased primarily as beauty and anti-ageing products rather than food. As a result, the company’s claim for a VAT refund of approximately £3.64 million was unsuccessful.
Why does this matter?
Under UK VAT law, most basic food and grocery items are zero-rated. However, there are a number of specific exceptions meaning that some products which consumers would regard as food are nevertheless subject to VAT at the standard rate.
One of the best-known examples is the Jaffa Cakes case. The dispute arose because cakes are generally zero-rated, whereas chocolate-covered biscuits are standard-rated. Although consumers would regard both as food, the VAT treatment depended on which category the product fell into. The courts ultimately concluded that Jaffa Cakes were cakes and therefore qualified for zero-rating.
The recent Minerva Research Labs decision demonstrates that similar issues continue to arise today. In Minerva, the question was not whether the product fell within an exception to the food rules, but whether the collagen beauty drinks constituted food at all. As with Jaffa Cakes, the Tribunal looked beyond the ingredients and considered the overall characteristics of the product, including how it was marketed, consumed and perceived by the ordinary consumer.
Many businesses assume that if a product is edible, drinkable or contains nutritional ingredients, it should qualify for VAT zero-rating. However, the UK’s VAT rules are rarely that straightforward.
When deciding whether a product qualifies for zero-rating, the courts frequently consider factors such as:
- How the product is marketed
- Why consumers purchase it
- How it is packaged and labelled
- How it is consumed
- How the average consumer would perceive it
The Minerva Research Labs decision reinforces the principle that nutritional value alone is not enough to secure zero-rating.
A history of VAT disputes over food and drink
The case joins a long line of disputes that demonstrate how difficult VAT classification can be for innovative products.
Other notable examples include:
- Walkers Sensations Poppadoms, where the courts considered whether the product fell within the exception for ‘potato crisps and similar products’, which are standard-rated for VAT. Walkers argued that the product was a poppadom-based savoury snack rather than a crisp and therefore remained zero-rated as food. HMRC successfully argued that, despite the ingredients used, the product was sufficiently similar to a potato crisp in terms of its characteristics and consumption to fall within the standard-rated exception.
- Mega Marshmallows, where HMRC argued that oversized marshmallows marketed for roasting were standard-rated confectionery. After extensive litigation, the taxpayer succeeded because the Tribunal found that the products were more commonly roasted or used in s’mores than eaten directly by hand and therefore did not fall within the statutory definition of confectionery. As a result, they qualified for zero-rating.
- Sports nutrition products, including cases involving protein and energy products, where the courts have had to consider whether products are ordinary food, dietary supplements or something else entirely for VAT purposes.
These cases illustrate that products sitting between traditional categories often create uncertainty and, in some cases, significant financial exposure.
What can businesses learn?
For food manufacturers, supplement providers, wellness brands and retailers, the key lesson is that VAT treatment is influenced not only by a product’s ingredients but also by its overall character and how it is presented to consumers.
As innovation continues to blur the lines between food, drink, supplements, cosmetics and health products, businesses should review VAT treatment carefully and at an early stage. A seemingly small difference in classification can have substantial consequences where products are sold at scale.
Our view
The latest Tribunal decision is another reminder that the UK’s VAT regime for food and drink is heavily influenced by detailed legislative provisions and decades of case law. While consumers may see little difference between food products, supplements and wellness products, the VAT consequences can be dramatically different.
Businesses launching new products should seek advice before adopting a VAT position, particularly where products do not fit neatly within traditional categories. As the Minerva Research Labs case demonstrates, the distinction between a food product and a wellness product can be worth millions of pounds in VAT.